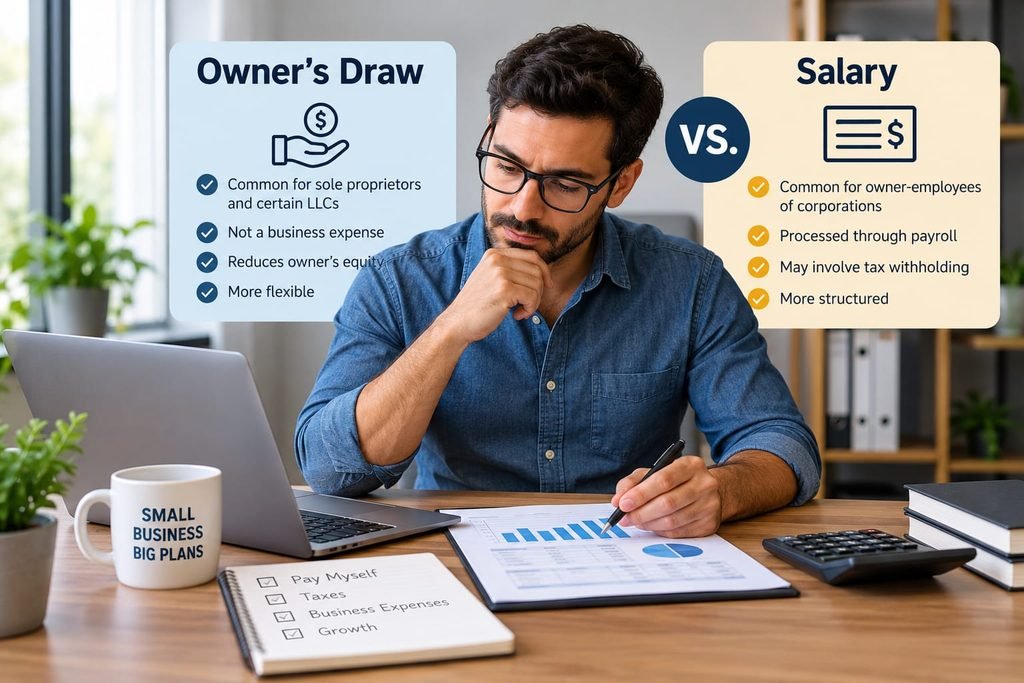
Paying yourself is one of the most important decisions you will make as a small business owner. You need money to cover your personal expenses, but you also need enough cash in your business to pay bills, invest in growth, and prepare for taxes.
Two common terms you will encounter are owner’s draw and salary. Although both can put money in your pocket, they work differently and are not interchangeable for every type of business.
Understanding owner’s draw vs. salary can help you choose the appropriate payment method for your business structure, maintain accurate financial records, and avoid common tax mistakes.
In this guide, you will learn how owner’s draws and salaries work, how different business structures affect the way you pay yourself, and how to establish a practical payment routine.
What Is an Owner’s Draw?
An owner’s draw is money a business owner withdraws from the business for personal use. It is commonly used by sole proprietors and owners of certain LLCs that are not taxed as corporations.
For example, imagine you operate a small consulting business as a sole proprietor. Your business earns revenue, pays operating expenses, and generates a profit. You can transfer some of the available business funds to your personal bank account to cover rent, groceries, or other personal expenses.
That transfer is an owner’s draw.
An owner’s draw is generally not treated as a business operating expense. Instead, it reduces the owner’s equity in the business.
How Does an Owner’s Draw Work?
The process is relatively simple:
- Calculate your business income and operating expenses.
- Review your available cash and upcoming financial obligations.
- Determine how much money you can safely withdraw.
- Transfer the money from your business account to your personal account.
- Record the transaction as an owner’s draw in your accounting records.
For example, suppose your business has $8,000 in available cash after collecting customer payments. You need $3,000 for upcoming bills, inventory, and other business obligations. You decide to withdraw $1,000 for personal expenses.
You would record the $1,000 transfer as an owner’s draw rather than a business expense.
However, available cash is not necessarily the same as profit. Before withdrawing money, consider unpaid invoices, taxes, loan payments, and other upcoming obligations.
What Is a Salary?
A salary is compensation paid to someone for work performed. Business owners who are also employees of their corporations may receive salaries through a formal payroll system.
Unlike an owner’s draw, a salary is generally processed as employee compensation. Depending on the circumstances, payroll may involve income tax withholding, Social Security and Medicare taxes, payroll reporting, and other employer responsibilities.
For example, suppose you own a corporation and work as its full-time manager. The corporation pays you a regular salary through payroll for the services you provide.
The company records the salary as compensation expense, subject to the applicable accounting and tax rules.
How Does a Business Owner Receive a Salary?
When the business structure requires or permits the owner to receive employee compensation, the process generally involves:
- Establishing appropriate compensation.
- Setting up payroll records and the required tax accounts.
- Calculating wages and applicable withholdings.
- Paying the owner through payroll.
- Filing the required payroll forms and reports.
The exact requirements depend on the business structure and tax classification.
For example, corporate officers who perform services for their corporations are generally considered employees when they receive or are entitled to compensation. Special rules also apply to owners who work for S corporations.
Owner’s Draw vs. Salary: Key Differences
Although owner’s draws and salaries both provide money to business owners, they differ in how they are recorded and treated for tax purposes.
1. Who Can Use Each Method?
Owner’s draws are commonly used by sole proprietors and owners of LLCs taxed as sole proprietorships or partnerships.
Salaries are generally used when an owner works as an employee of a corporation.
The business’s legal structure alone may not tell the whole story. Its federal tax classification also matters.
2. How Are They Recorded?
An owner’s draw is generally recorded as a reduction in the owner’s equity rather than an operating expense.
A salary is generally recorded as compensation expense for the corporation, subject to the applicable accounting rules.
Keeping these transactions separate makes it easier to understand business profitability and prepare accurate financial statements.
3. How Are Taxes Handled?
An owner’s draw does not automatically determine how much tax the owner owes.
For example, a sole proprietor generally reports taxable business profit even if some of that profit remains in the business instead of being withdrawn.
A salary, on the other hand, is generally processed through payroll when the owner is an employee. Applicable withholding and employment tax rules must be followed.
The specific tax consequences depend on the owner’s circumstances and the business’s tax classification.
4. Is the Payment Flexible?
Owner’s draws can offer flexibility because the owner may withdraw available funds without establishing a traditional salary.
However, flexibility does not mean unlimited withdrawals are financially wise. A business still needs sufficient cash to meet its obligations.
A salary typically follows a more structured payroll schedule. This can help the owner establish predictable personal income while maintaining consistent payroll records.
Owner’s Draw vs. Salary Comparison Table
Owner’s Draw:
- Commonly used by sole proprietors and certain LLC owners.
- Generally reduces owner’s equity.
- Is not usually a deductible operating expense.
- Does not automatically create payroll withholding.
- The owner’s tax liability generally depends on taxable business income and applicable tax rules.
Salary:
- Commonly used for owner-employees of corporations.
- Generally recorded as compensation expense.
- Is processed through payroll when applicable.
- May involve income tax withholding and employment taxes.
- Must comply with the relevant compensation and payroll rules.
The most appropriate method depends on your business structure and federal tax classification.
How Your Business Structure Affects How You Pay Yourself
Before deciding between an owner’s draw and a salary, identify how your business is classified for federal tax purposes.
Different business structures follow different rules.
Sole Proprietorship
A sole proprietor generally does not receive a salary from their own business.
Instead, the owner can take money out of the business through owner’s draws.
The business’s net profit is generally reported on the owner’s individual tax return, regardless of how much money the owner withdraws.
For example, if your business generates $60,000 in net profit during the year and you withdraw $35,000 for personal use, your taxable business profit is not automatically reduced to $35,000.
Your tax calculation depends on the applicable deductions and tax rules, not simply on the amount withdrawn.
Single-Member LLC
A single-member LLC is generally treated as a disregarded entity for federal income tax purposes unless it elects corporate tax treatment.
When the owner is an individual and the LLC uses this default classification, the owner generally takes draws rather than receiving a salary from the LLC.
However, an LLC can elect to be taxed as a corporation. If it does, the rules may change.
Always confirm your LLCs federal tax classification before choosing a payment method.
Partnership
Partners in a partnership are generally not employees of the partnership for federal tax purposes and should not receive a Form W-2 for their distributions or guaranteed payments.
Partners may receive distributions or guaranteed payments, depending on the arrangement and applicable tax rules.
These payments are not necessarily equivalent to an employee salary.
If your business has multiple owners, establish clear procedures for recording distributions and determining each partner’s financial entitlements.
S Corporation
An S corporation has different rules from a sole proprietorship.
When a shareholder performs substantial services for the corporation, the corporation generally must pay reasonable compensation for those services before making non-wage distributions to that shareholder-employee.
The salary must be processed through payroll, with applicable employment taxes and reporting.
An owner cannot simply classify all payments as distributions to avoid employment taxes.
The appropriate salary depends on factors such as the owner’s responsibilities, experience, working hours, and compensation for comparable work.
C Corporation
A C corporation is a separate legal and tax entity.
An owner who works for the corporation is generally treated as an employee when receiving compensation for services.
The corporation may pay a salary through payroll. Shareholders may also receive dividends when properly authorized and supported by the corporation’s financial position and applicable law.
Salary and dividends have different tax treatments, so they should not be treated as interchangeable.
Consult a qualified tax professional before deciding how to structure payments from a corporation.
Is an Owner’s Draw Taxable?
One of the most common misconceptions about owner’s draws is that the withdrawal itself determines the owner’s taxable income.
For a sole proprietor, that is generally not how federal income taxation works.
The owner is generally taxed on the business’s taxable profit, not simply on the amount transferred to a personal bank account.
Consider this example:
Your business generates $50,000 in net profit during the year.
You withdraw $20,000 for personal expenses and leave the remaining $30,000 in the business.
Your taxable business profit does not automatically become $20,000. The amount generally remains $50,000 before any additional applicable tax adjustments.
This distinction is important because business owners can owe taxes even when they leave some of their profits in the business.
Depending on the business structure and circumstances, the owner may also owe self-employment tax and may need to make estimated tax payments.
Corporations and partnerships follow different rules, so do not apply the sole proprietor example to every business.
For additional guidance, consult the IRS page on Paying Yourself.
How Much Should You Pay Yourself?
There is no single amount that works for every small business owner.
Your payment strategy should reflect both your personal financial needs and your business’s ability to meet its obligations.
1. Calculate Your Business Profit
Start by reviewing your revenue and expenses.
Calculate how much your business earns after operating costs, and remember that accounting profit and available cash are not always the same.
A profitable business may still have cash tied up in unpaid invoices or inventory.
2. Review Your Cash Flow
Check how much money is available in your business bank account.
Then consider upcoming expenses, including:
- Rent and utilities.
- Employee wages.
- Inventory and supplies.
- Loan repayments.
- Insurance.
- Tax payments.
- Emergency reserves.
Avoid withdrawing money that your business needs to operate.
3. Establish a Consistent Payment Routine
If your business uses owner’s draws, consider setting a regular withdrawal schedule, such as monthly or twice a month.
A consistent routine makes it easier to manage personal finances and track withdrawals.
If your business requires payroll, follow the appropriate payroll schedule and reporting procedures.
4. Set Aside Money for Taxes
Do not assume that money withdrawn from your business is free from tax obligations.
Estimate your tax liability based on your business structure and financial results.
If you are self-employed, you may need to make estimated tax payments during the year.
A tax professional can help you determine the appropriate amount to reserve.
5. Review Your Payment Amount Regularly
Your business income may change from month to month.
Review your cash flow, profitability, and financial obligations regularly. If revenue declines or expenses increase, you may need to adjust your draws or review your compensation arrangements.
The goal is to maintain a balance between personal financial stability and business sustainability.
Common Mistakes to Avoid
Choosing the right payment method is only part of the process. You must also maintain accurate records and follow the relevant tax rules.
Treating an Owner’s Draw as a Business Expense
An owner’s draw is generally an equity transaction, not an ordinary operating expense.
Recording it as an expense can understate your reported business profit.
Use the appropriate owner’s equity or draw account in your accounting system.
Mixing Personal and Business Transactions
Using your business bank account for personal purchases without proper documentation can make bookkeeping more difficult.
Maintain separate business and personal accounts where appropriate, and record transfers accurately.
For LLCs and corporations, maintaining clear separation between business and personal transactions is particularly important.
Ignoring Tax Obligations
Taking an owner’s draw does not automatically eliminate or reduce your tax liability.
Likewise, paying yourself a salary does not remove the need to follow payroll reporting requirements.
Understand which taxes apply to your business and plan for them throughout the year.
Paying S Corporation Distributions Instead of Reasonable Wages
An S corporation shareholder who performs services for the business generally cannot avoid employment taxes simply by taking distributions instead of reasonable compensation.
The corporation must follow the applicable wage and payroll rules.
Review the IRS guidance on S Corporation Compensation and Medical Insurance Issues.
Withdrawing Too Much Money
Even when an owner can legally take a draw, excessive withdrawals may leave the business unable to pay suppliers, employees, or other bills.
Review upcoming obligations before transferring funds to your personal account.
Failing to Keep Accurate Records
Record each draw, salary payment, distribution, or guaranteed payment using the appropriate account.
Keep supporting documentation and reconcile your bank accounts regularly.
Good records make it easier to prepare financial statements, monitor cash flow, and work with your accountant.
How to Record Owner’s Draws and Salary in Your Books
Accurate bookkeeping helps you understand how much money you take out of the business and how those payments affect your financial records.
The accounting treatment depends on the type of payment.
Recording an Owner’s Draw
Suppose you transfer $1,000 from your business bank account to your personal bank account.
For a business using owner’s draws, the simplified bookkeeping entry is:
Debit: Owner’s Draw — $1,000
Credit: Business Cash — $1,000
This entry records the withdrawal and reduces the owner’s equity. It does not record a business operating expense.
The exact account names may vary depending on your accounting software and chart of accounts.
Recording a Salary Payment
For a corporation that pays an owner-employee through payroll, the accounting entry is more complex.
It generally records gross wages as compensation expense and accounts for the relevant payroll withholdings, employer taxes, and net payment.
For example, the employee’s gross salary is not necessarily the same as the amount deposited into their personal account because payroll deductions may apply.
Use payroll software or work with a qualified payroll professional to ensure the entries and filings are correct.
Keep Draws, Salaries, and Distributions Separate
Do not combine every payment to the owner into one general expense account.
Separate records make it easier to determine:
- How much the owner withdrew.
- How much the business paid in wages.
- Whether shareholder distributions were made.
- How much the business spent on operating expenses.
- Whether the accounting records match the bank statements.
This information also helps your accountant prepare the appropriate tax returns.
Frequently Asked Questions
Is an owner’s draw better than a salary?
Neither method is universally better.
An owner’s draw is commonly used by sole proprietors and certain LLC owners. A salary is generally used when an owner is an employee of a corporation.
Your business structure and tax classification determine which method is appropriate.
Can I pay myself a salary as a sole proprietor?
Generally, no. For federal tax purposes, a sole proprietor is not an employee of their own business and cannot deduct their own salary as a business expense.
Sole proprietors commonly take owner’s draws instead.
Do owner’s draws reduce business profit?
No. An owner’s draw generally reduces the owner’s equity rather than the business’s operating profit.
It is a withdrawal of business funds for personal use, not a deductible business expense.
Do I pay taxes on an owner’s draw?
Your tax obligations generally depend on your taxable business income and business structure, not simply on the amount withdrawn.
For example, a sole proprietor generally reports business profit even if some of that money remains in the business.
Other business structures may follow different rules.
Can an S corporation owner take both a salary and distributions?
Yes, when applicable requirements are met.
An S corporation shareholder-employee who performs services generally must receive reasonable compensation before taking non-wage distributions.
The salary must be processed through payroll and comply with the relevant tax rules.
How often should I pay myself?
The appropriate frequency depends on your business structure, cash flow, and personal needs.
An owner who takes draws may establish a regular withdrawal schedule. An owner receiving a salary should follow the corporation’s payroll procedures.
Review your financial position before establishing or changing a payment routine.
What is the difference between an owner’s draw and a distribution?
The terms are sometimes used informally in similar ways, but their legal and tax meanings depend on the business structure.
An owner’s draw commonly refers to withdrawals by a sole proprietor or certain LLC owners. A corporate distribution is a payment made to a shareholder under the applicable corporate and tax rules.
Do not assume that the two transactions have identical accounting or tax treatment.
Final Thoughts
Understanding owner’s draw vs. salary is essential for managing your personal income and maintaining accurate business records.
Owner’s draws are commonly used by sole proprietors and certain LLC owners, while salaries are generally used when business owners work as employees of corporations.
The right approach depends on your business structure, federal tax classification, cash flow, and applicable tax rules.
Before making a decision, confirm how your business is classified, maintain accurate financial records, and plan for taxes and operating expenses.
If you are unsure which method applies to your