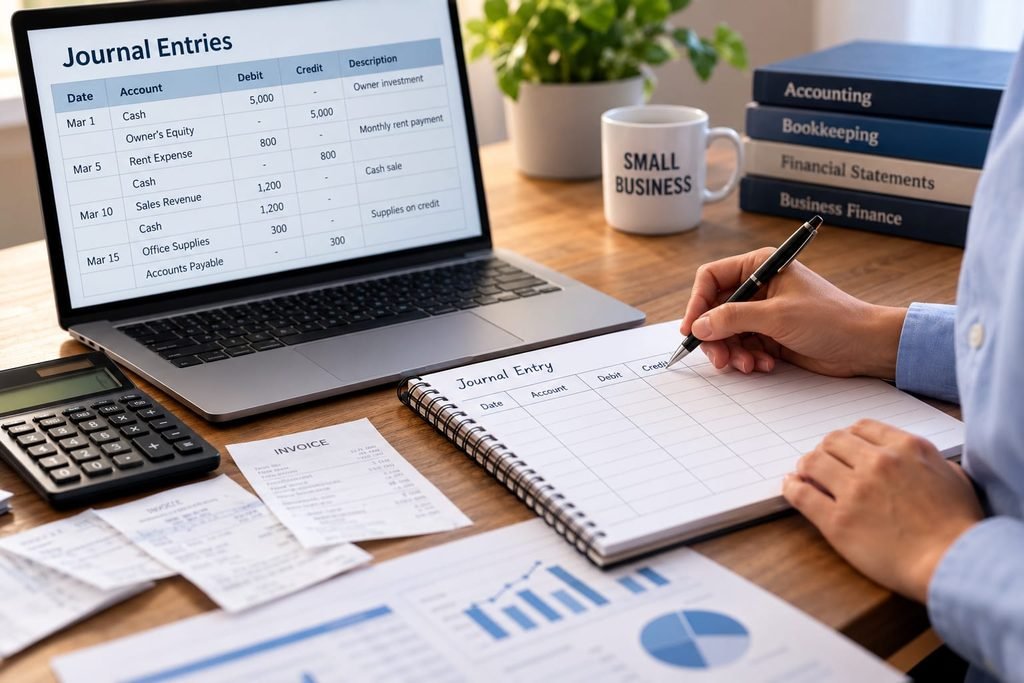
Every small business needs accurate financial records to track income, expenses, and other transactions. One of the most important parts of maintaining these records is understanding journal entries.
Journal entries for small business accounting help owners record financial transactions systematically. Whether your business receives a customer payment, purchases supplies, pays rent, or takes out a loan, recording the transaction correctly helps keep your books organized.
You do not need to be an accountant to understand the basics. By learning how debits and credits work, you can improve your bookkeeping, understand financial reports, and prepare more effectively for tax season.
In this guide, you will learn what journal entries are, how to record them, practical examples, common mistakes to avoid, and best practices for keeping your business records accurate.
What Are Journal Entries in Small Business Accounting?
A journal entry is a record of a financial transaction in an accounting system. It typically includes the transaction date, the accounts affected, debit and credit amounts, and a brief description.
For example, suppose your business pays $500 for office supplies using its business bank account. The transaction affects two accounts:
- Office Supplies Expense increases by $500.
- Cash decreases by $500.
The journal entry records both effects of the transaction.
In double-entry accounting, every journal entry must have equal total debits and credits. This principle helps maintain balanced accounting records.
Businesses record transactions in a journal before organizing them by account in the general ledger. Keeping supporting documents, such as receipts and invoices, helps explain and verify each transaction.
For additional guidance, see the IRS guide to recording business transactions.
Why Are Journal Entries Important for Small Businesses?
Journal entries are important because they provide a structured record of your business’s financial activity.
1. Track Business Income and Expenses
Recording transactions helps you understand how much money your business earns and spends. You can review sales, rent, supplies, utilities, and other operating costs.
2. Maintain Accurate Financial Statements
Journal entries provide information used to prepare financial statements, including the income statement and balance sheet. Accurate entries help ensure that these reports reflect your business’s financial activity more reliably.
3. Identify Accounting Errors
Regularly reviewing journal entries can help you identify duplicate transactions, incorrect amounts, missing entries, and transactions recorded in the wrong accounts.
4. Support Tax Preparation
Organized accounting records make it easier to review business income and expenses when preparing tax returns. Receipts, invoices, bank statements, and other supporting documents can help explain the transactions recorded in your books.
The IRS provides guidance on recordkeeping for small businesses and self-employed individuals.
5. Make Better Business Decisions
Reliable records help you evaluate spending, monitor revenue, and understand your business’s financial performance. This information can support decisions about budgeting, purchasing, and future growth.
Understanding Debits and Credits
Debits and credits are the foundation of double-entry accounting. Every journal entry must have total debits equal to total credits.
A debit is recorded on the left side of an account, while a credit is recorded on the right side. Whether an entry increases or decreases an account depends on the account type.
| Account Type | Increase | Decrease |
|---|---|---|
| Assets | Debit | Credit |
| Expenses | Debit | Credit |
| Liabilities | Credit | Debit |
| Equity | Credit | Debit |
| Revenue | Credit | Debit |
For example, when your business receives $1,000 from a customer for a completed sale, Cash increases with a debit and Sales Revenue increases with a credit.
| Account | Debit | Credit |
|---|---|---|
| Cash | $1,000 | $0 |
| Sales Revenue | $0 | $1,000 |
| Total | $1,000 | $1,000 |
The two sides balance because the total debit equals the total credit.
Remember that a debit does not always mean money entering the business, and a credit does not always mean money leaving it. Their effect depends on the accounts involved.
The Main Parts of a Journal Entry
A journal entry usually contains several important details.
Transaction Date
The date identifies when the transaction occurred or when it should be recognized under the accounting method your business uses.
Account Names
Account names identify which parts of the accounting records are affected. Examples include Cash, Accounts Receivable, Accounts Payable, Sales Revenue, and Rent Expense.
Debit and Credit Amounts
Each entry records the amounts debited and credited. The totals must be equal under the double-entry accounting system.
Description or Memo
A short description explains the transaction and makes it easier to understand during a later review.
Supporting Documentation
Receipts, invoices, bank statements, contracts, and payment confirmations provide evidence of business transactions.
Keeping supporting documentation organized is an important part of maintaining reliable financial records. You can review the IRS recordkeeping guidance for more information.
How to Record Journal Entries Step by Step
Follow these steps to record a basic business transaction.
Step 1: Identify the Transaction
Determine what happened. Your business may have made a sale, paid a bill, purchased equipment, received a loan, or collected money from a customer.
Check the available documentation to confirm the transaction details.
Step 2: Identify the Accounts Affected
Determine which accounts changed because of the transaction.
For example, paying rent affects Rent Expense and Cash. Receiving a business loan affects Cash and Loan Payable.
Step 3: Determine Which Accounts Increase or Decrease
Decide whether each account increases or decreases based on the transaction.
When a business pays rent from its bank account, Rent Expense increases and Cash decreases.
Step 4: Apply the Debit and Credit Rules
Use the account types to determine which amounts should be debited and credited.
For a rent payment, debit Rent Expense and credit Cash.
Step 5: Enter the Amounts
Record the correct amount for each account. Verify that total debits equal total credits.
Step 6: Add a Description and Supporting Documents
Write a brief explanation and retain the relevant receipt, invoice, or payment confirmation.
Step 7: Review and Post the Entry
Check the entry for accuracy and post it to the appropriate accounts. Accounting software may automate posting, but you should still review transactions and investigate unusual entries.
Journal Entry Examples for Small Businesses
The following examples demonstrate how to record common transactions. The amounts are illustrative and may differ from your business’s actual transactions.
Example 1: Owner Invests $5,000 in the Business
Suppose an owner contributes $5,000 to the business in exchange for an ownership interest.
| Account | Debit | Credit |
|---|---|---|
| Cash | $5,000 | $0 |
| Owner’s Equity | $0 | $5,000 |
| Total | $5,000 | $5,000 |
Explanation: Cash increases because the business receives money. Owner’s Equity increases because the owner contributes funds to the business.
The appropriate account and treatment depend on the business’s legal structure and accounting arrangements.
Example 2: Business Pays $800 in Rent
Suppose the business pays $800 in monthly rent from its bank account.
| Account | Debit | Credit |
|---|---|---|
| Rent Expense | $800 | $0 |
| Cash | $0 | $800 |
| Total | $800 | $800 |
Explanation: Rent Expense increases, while Cash decreases because the business has paid the landlord.
Example 3: Business Makes a $1,200 Cash Sale
Suppose your business makes a sale for $1,200 and receives payment immediately.
| Account | Debit | Credit |
|---|---|---|
| Cash | $1,200 | $0 |
| Sales Revenue | $0 | $1,200 |
| Total | $1,200 | $1,200 |
Explanation: Cash increases, and Sales Revenue increases.
If the transaction involves inventory, an additional entry may be required to record the cost of goods sold and the reduction in inventory.
Example 4: Business Purchases $300 of Office Supplies on Credit
Suppose your business purchases $300 of office supplies but agrees to pay the supplier later.
| Account | Debit | Credit |
|---|---|---|
| Office Supplies Expense | $300 | $0 |
| Accounts Payable | $0 | $300 |
| Total | $300 | $300 |
Explanation: The expense increases, and Accounts Payable increases because the business owes the supplier money.
Depending on the nature of the purchase and the business’s accounting policy, some supplies may initially be recorded as an asset instead of an expense.
Example 5: Business Pays a $300 Supplier Invoice
Suppose the business pays the supplier invoice recorded in Example 4.
| Account | Debit | Credit |
|---|---|---|
| Accounts Payable | $300 | $0 |
| Cash | $0 | $300 |
| Total | $300 | $300 |
Explanation: Accounts Payable decreases, and Cash decreases because the business pays the supplier.
The payment does not create the same expense a second time because the expense was recorded when the original purchase was recognized.
Example 6: Business Receives a $10,000 Loan
Suppose a lender deposits $10,000 into your business bank account.
| Account | Debit | Credit |
|---|---|---|
| Cash | $10,000 | $0 |
| Loan Payable | $0 | $10,000 |
| Total | $10,000 | $10,000 |
Explanation: Cash increases, and Loan Payable increases because the business must repay the lender.
Receiving loan proceeds is generally not the same as earning revenue. Interest and principal payments must be accounted for appropriately when payments begin.
Journal Entries vs. the General Ledger
Journal entries and the general ledger are closely connected, but they serve different purposes.
A journal records transactions in chronological order. The general ledger organizes those transactions by account so you can review the activity and balance of each account.
For example, a journal may show rent payments, customer receipts, and supplier purchases in the order they occurred. The general ledger groups the relevant entries under Cash, Rent Expense, Sales Revenue, and Accounts Payable.
Journal Entries vs. the Trial Balance
A journal entry records an individual transaction. A trial balance is a report listing the balances of ledger accounts at a particular point in time.
Businesses can use a trial balance to check whether total debit balances equal total credit balances.
However, a balanced trial balance does not guarantee that every transaction is correct. For example, a transaction may have been recorded in the wrong expense account while still keeping total debits equal to total credits.
Reviewing transaction details remains important.
Manual Journal Entries vs. Accounting Software
Small businesses can record journal entries manually in a spreadsheet or use accounting software.
Manual Journal Entries
A spreadsheet can be useful for a new business with a small number of transactions. It allows the owner to organize dates, account names, debits, credits, and descriptions.
However, spreadsheets require careful maintenance. Errors in formulas, missing transactions, and inconsistent account names can affect the accuracy of the records.
Accounting Software
Accounting software can automate many routine entries, organize transactions, and generate reports.
Depending on the software and settings, bank feeds, invoices, customer payments, and supplier bills may automatically create accounting entries.
Even when software automates the process, business owners should review transactions and investigate unusual balances.
Common Journal Entry Mistakes to Avoid
Small business owners should watch for these common mistakes.
Recording Only One Side of a Transaction
Double-entry accounting requires equal total debits and credits. Recording only one side can make the books incomplete or unbalanced.
Using the Wrong Account
Recording a loan as sales revenue or treating an owner’s contribution as business income can distort financial reports.
Choose accounts based on the actual nature of each transaction.
Entering Duplicate Transactions
Recording the same invoice or payment twice can overstate expenses, income, assets, or liabilities.
Compare entries with receipts, invoices, and bank activity to identify duplicates.
Recording Transactions in the Wrong Period
Incorrect dates can affect monthly reports and financial statements. Use the appropriate date based on the transaction and your accounting method.
Ignoring Supporting Documentation
A transaction description alone may not provide enough evidence to explain a payment months later. Keep invoices, receipts, contracts, and other relevant documents.
Failing to Review Journal Entries
Review entries periodically to identify unusual amounts, unexpected account balances, and transactions that need clarification.
Best Practices for Managing Journal Entries
Use these practices to maintain accurate accounting records:
- Record transactions consistently and promptly.
- Use a clear and consistent chart of accounts.
- Include useful descriptions for transactions.
- Keep supporting documents organized.
- Review bank transactions and reconcile accounts regularly.
- Separate personal and business transactions.
- Review unusual entries before closing each accounting period.
- Back up digital records and protect access to accounting systems.
- Seek help from a qualified accounting professional when transactions are complex.
The U.S. Small Business Administration’s guide to managing business finances provides additional guidance on keeping your business finances organized.
Frequently Asked Questions
What Is a Journal Entry in Small Business Accounting?
A journal entry is a record of a financial transaction that identifies the accounts affected and the debit and credit amounts. It helps maintain organized accounting records.
Do All Journal Entries Need a Debit and a Credit?
Under the double-entry accounting system, each journal entry must contain equal total debits and credits. Some transactions require more than two account lines, but the totals must still match.
Can I Record Journal Entries in Excel?
Yes. You can use Excel or Google Sheets to record basic journal entries. Your spreadsheet should include the date, account names, debit amounts, credit amounts, and transaction descriptions. You must also check that total debits equal total credits.
How Often Should a Small Business Record Journal Entries?
Transactions should be recorded consistently and promptly. The ideal frequency depends on transaction volume, the accounting method, and reporting requirements. Many businesses record transactions throughout the month and review their records at month-end.
What Is the Difference Between a Journal and a Ledger?
A journal records transactions in chronological order. A ledger groups those transactions by account, helping you track account activity and balances.
Should Small Business Owners Learn Journal Entries?
Understanding the basics helps owners read financial reports, review bookkeeping work, and identify possible errors. A professional bookkeeper or accountant can assist with complex transactions and reporting requirements.
Conclusion
Journal entries are a fundamental part of small business accounting. They help record income, expenses, assets, liabilities, and equity while maintaining balanced financial records.
By identifying the accounts affected, applying debit and credit rules, keeping supporting documents, and reviewing entries regularly, you can improve the accuracy of your bookkeeping.
Start with simple transactions and use a consistent process. As your business grows, accounting software or professional guidance can help you maintain reliable records and make better financial decisions.
Pingback: Debits and Credits for Small Business: A Simple Guide
Pingback: Depreciation for Small Business: How It Works