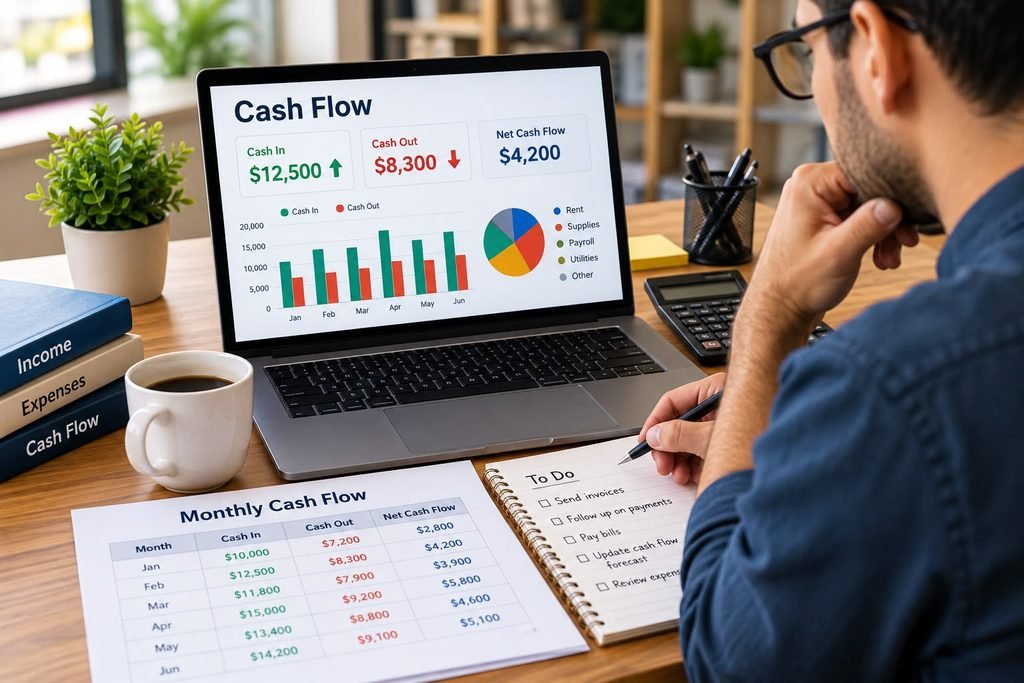
Small business cash flow is the movement of money into and out of your business. Money comes in when customers pay you, and money goes out when you pay for rent, supplies, payroll, software, taxes, and other costs. What matters is how much cash you have available at any given time.
Cash flow matters because a business can only pay its bills with cash it actually has. It also isn’t the same as profit. You can make a sale, send an invoice, and look profitable on paper while still waiting weeks for the money to arrive.
This guide explains what small business cash flow is, how it differs from profit, how to track it, how to build a simple forecast, and how to improve it. It ends with a weekly routine and three checklists you can use right away.
What Is Small Business Cash Flow?
Cash flow describes three simple things:
- Cash coming in: customer payments, cash sales, loan proceeds, or money an owner puts into the business.
- Cash going out: rent, payroll, inventory, supplies, vendor bills, loan payments, taxes, and other costs.
- Cash remaining: what is left after inflows and outflows.
Say Priya runs a small print shop. In March, she collects $9,000 from customers and pays out $7,500 for rent, paper, ink, and a part-time employee. Her cash flow for the month is $1,500 positive. If she had paid out $10,000 instead, her cash flow would be negative by $1,000, and she would need to draw on savings or find other cash to cover it.
Why Cash Flow Matters for Small Businesses
Healthy cash flow helps a business:
- Pay employees and vendors on time
- Cover operating expenses such as rent and utilities
- Handle unexpected costs like equipment repairs
- Plan upcoming payments with fewer surprises
- Avoid unnecessary financial stress
- Continue operating and growing
Cash flow problems often show up before any other sign of trouble, which is why it pays to watch it closely.
Cash Flow vs. Profit
Profit and cash flow are related, but they measure different things. Profit looks at income compared with expenses. Cash flow looks at when money actually moves in and out of your account.
Here is a simple example. A business completes a $5,000 job in January and sends an invoice due in 45 days. In the same month, it pays $3,000 in expenses. On paper, the job looks profitable. But the customer hasn’t paid yet, so the bank account is down $3,000 for now. The money only becomes available when the customer pays.
How income and expenses are recorded depends on your accounting method (cash or accrual), so talk to a qualified professional if you’re unsure which applies to you. The practical lesson is the same either way: look at your bank balance and your upcoming payments, not just your sales.
The Three Types of Cash Flow
Cash flow is often grouped into three categories. Most small businesses deal mainly with the first.
Operating Cash Flow
This is cash generated or used by normal day-to-day operations. It includes customer payments and spending on payroll, rent, inventory, and supplies.
Investing Cash Flow
This is cash used for or received from business assets and investments. Buying equipment or a vehicle is an outflow. Selling equipment is an inflow.
Financing Cash Flow
This is money coming from or going to loans, owners, or other financing. Receiving a business loan or an owner contribution is an inflow. Making loan payments or owner withdrawals is an outflow.
How to Track Small Business Cash Flow
A simple tracking system answers one question: how much cash do I have now, and how much will I have soon? Track these items:
- Beginning cash balance
- Cash received
- Cash spent
- Ending cash balance
- Expected incoming money
- Upcoming payments
A spreadsheet works well for many small businesses. Accounting software can help as your transactions grow, since it can pull in bank activity and show balances automatically. Whichever you choose, update it regularly so the numbers stay useful.
What to Include in a Cash Flow Statement
A basic cash flow statement for a small business covers:
- Beginning cash balance: cash on hand at the start of the period
- Cash inflows: money received during the period
- Cash outflows: money paid out during the period
- Net cash flow: inflows minus outflows
- Ending cash balance: beginning balance plus net cash flow
For example, if you start the month with $4,000, receive $12,000, and spend $10,500, your net cash flow is $1,500 and your ending balance is $5,500.
How to Create a Simple Cash Flow Forecast
A cash flow forecast estimates your future cash balance so you can spot shortages before they happen.
- Start with current cash. Use your actual bank balance.
- Estimate expected income. Base it on current orders, recurring customers, and past sales.
- List upcoming expenses. Include rent, payroll, bills, loan payments, and planned purchases.
- Estimate when customers will actually pay. Use due dates and how quickly customers usually pay, not the invoice date.
- Calculate the expected cash balance. Add expected income to current cash and subtract expenses, period by period.
- Review the forecast regularly. Update it with actual results.
A forecast is an estimate, not a promise. Sales may come in higher or lower, and bills can change, so adjust it as circumstances change.
Common Small Business Cash Flow Problems
Most cash flow problems come from a few familiar sources:
- Customers paying late: Money you have earned arrives after your own bills are due.
- Large unexpected expenses: A repair or replacement can drain cash quickly.
- Seasonal sales: Slow months still have rent and payroll.
- Overspending: Small, regular expenses can add up unnoticed.
- Poor payment timing: Paying bills much earlier than necessary can leave you short.
- Too much money tied up in inventory: Stock you haven’t sold isn’t available as cash.
- High debt payments: Fixed loan payments reduce flexibility.
- Not planning for taxes and other large expenses: Big bills are easier to handle when you set money aside in advance.
How to Improve Small Business Cash Flow
Invoice Customers Promptly
The sooner an invoice goes out, the sooner the payment clock starts. See our guide to small business invoicing for how to create clear invoices.
Follow Up on Unpaid Invoices
Send friendly reminders before and shortly after due dates instead of waiting until an invoice is seriously late.
Review Business Expenses
Look at recurring costs regularly and cancel or reduce anything you no longer need.
Manage Inventory Carefully
Buy what you expect to sell, so cash isn’t sitting on shelves.
Plan Large Purchases
Check your forecast before committing to a big expense so it doesn’t create a shortage later.
Negotiate Payment Terms When Appropriate
Some vendors may offer terms that fit your cash cycle. It’s reasonable to ask, and to read the terms on each invoice.
Maintain a Cash Reserve
A cash reserve gives you a cushion for slow periods and surprises. The right amount depends on your business, its costs, and how predictable its income is.
Review Cash Flow Regularly
A short weekly review catches problems while they are still easy to fix.
Accounts Receivable and Cash Flow
Accounts receivable is money customers owe your business for products or services you have already delivered. It isn’t cash until the customer pays. If a lot of money sits in unpaid invoices, your cash flow can feel tight even when sales are strong.
Tracking who owes you, how much, and since when helps you forecast incoming cash more realistically. For a step-by-step process, read our guide to accounts receivable for small business.
Accounts Payable and Cash Flow
Accounts payable is money your business owes to vendors. Unpaid bills represent future cash going out, so they belong in your forecast even before they are due.
Knowing which bills are due and when helps you avoid late fees and plan your payments around expected income. For more detail, see our guide to accounts payable for small business.
Business Bank Accounts and Cash Flow
When business and personal money are mixed in one account, it’s hard to tell how the business is really doing. A separate business account keeps deposits and expenses in one place, which makes your balance, your income, and your spending easier to track.
For more on setting one up and choosing what fits your business, see our guide to a business bank account for small business.
Simple Weekly Cash Flow Routine
A weekly review doesn’t need to take long. Set aside 20–30 minutes to:
- Check the current bank balance.
- Review money received.
- Review unpaid customer invoices.
- Check upcoming bills.
- Review unusual expenses.
- Update your cash flow forecast.
- Identify potential cash shortages early.
If you find a shortage coming, you have time to follow up on invoices, adjust spending, or talk to vendors.
Small Business Cash Flow Checklist
Daily or As Needed
- Record money received and money spent.
- Send new invoices promptly.
- Save receipts and bills.
- Note any unusual or large expenses.
Weekly
- Check your bank balance.
- Review unpaid invoices and upcoming bills.
- Follow up on overdue payments.
- Update your forecast.
- Look for possible shortages.
Monthly
- Review income and expenses.
- Compare your forecast with actual results.
- Review recurring costs and subscriptions.
- Review inventory, debt payments, and planned purchases.
- Make sure your bookkeeping is up to date.
Frequently Asked Questions
What is cash flow for a small business?
It is the movement of money into and out of the business, and the cash left after inflows and outflows.
Why is cash flow important?
A business needs cash on hand to pay employees, vendors, and expenses on time. Good cash flow also helps you handle surprises and plan ahead.
What is the difference between cash flow and profit?
Profit compares income with expenses. Cash flow tracks when money actually moves in and out of your account. A business can be profitable on paper and still be short of cash.
How can a small business improve cash flow?
Invoice promptly, follow up on unpaid invoices, review expenses, manage inventory, plan large purchases, negotiate payment terms when appropriate, keep a cash reserve, and review cash flow regularly.
How often should a small business track cash flow?
Record transactions as they happen and review your cash flow at least weekly. A monthly review helps you spot trends.
What causes cash flow problems?
Common causes include late customer payments, unexpected expenses, seasonal sales, overspending, poor payment timing, excess inventory, high debt payments, and not planning for large expenses like taxes.
What is a cash flow forecast?
It’s an estimate of the cash your business expects to receive and pay out over a future period, used to anticipate shortages and plan ahead.
Conclusion
Good small business cash flow management comes down to a few habits: tracking money coming in and going out, planning ahead, following up on unpaid invoices, controlling expenses, and reviewing your cash flow regularly. You don’t need complicated tools. A simple weekly routine and a basic forecast will show you where your money stands and help you act early.
For help keeping your records organized, see our small business bookkeeping guide, and consider working with a small business accountant if you have questions about your finances.
Pingback: Small Business Tax Deadlines: US Estimated Tax Calendar